Showing posts sorted by relevance for query margin of safety. Sort by date Show all posts

Monday, August 17, 2026

Edward Quince’s Wisdom Bites: Are You Intelligent? Chapter 20

We've reached the end. It's time we all learn Graham's secret.

The secret to sound investment is “MARGIN OF SAFETY”, so writes Graham in the opening paragraph of chapter 20.  As he says, “it is the thread that runs through all of the preceding discussion of investment policy.”  


So what is “margin of safety”, it is “rendering unnecessary an accurate estimate of the future.  If the margin is a large one, then it is enough to assume that future earnings will not fall below those of the past in order for an investor to feel sufficiently protected against the vicissitudes of time.”  


When considering this concept for common stock investments, Graham spoke of identifying the margin of safety as related to the earnings power of the company relative to the going rate for bonds.  You can probably just call this a sufficient “risk premium”.  Graham would consider the earnings yield (E/P) relative to risk-free rates, and if the earnings yield was 50% or more greater than the risk-free rate, Graham would consider that a very good margin of safety.


Graham goes on to caution that true earnings power typically can only come from observation over many years.  It is a note of caution against “growth stocks” and investors relying on optimistic projections of future earnings as the basis of “earnings power” when considering margin of safety.  He doesn’t dismiss growth stocks outright, simply cautions that some level of conservation is necessary in underwriting their future earnings.


Go all the way back to Chapter 1, remember that Graham defines investing as requiring deliberate protection against serious loss, any operation that fails to include that criteria is “speculation” in Graham’s book, thus Graham states: “we say that to have a true investment there must be present a true margin of safety. And a true margin of safety is one that can be demonstrated by figures, persuasive reasoning, and by a body of actual experience.”


Enterprising investing, or the business of investing is a tough business, Graham sets a high, business-oriented bar for those who are seeking to truly manage a stock portfolio.


But what about the rest of us, those who don’t want to try to hurdle that bar?  Graham’s advice is simple, stay the path of narrow defensive investment.  “To achieve satisfactory investment results is easier than most people realize; to achieve superior results is harder than it looks.”


Commenting on Commentary on Chapter 20

Zweig opens up his commentary with a simple question: “What is Risk?”  People posit many answers, but Zweig offers up simple advice, that investment risk is the possibility of losing all or most of your money.


Zweig reminds readers that risk is not simply about probabilities, it's equally about consequences.  He cites one of my favorite quotes from Bernstein’s book “Against The Gods”, stating: “In making decisions under conditions of uncertainty, the consequences must dominate the probabilities. We never know the future.”


The central theme of Graham’s teaching here is that investing isn’t just about getting the analysis right, you have to ensure that if you’re wrong you can survive. 


In years of thinking about risk, I think an often overlooked aspect of “risk” is the setting of goals, it’s knowing what you want to achieve.  I feel like this is fundamental to providing context to risk and it seems clear that misspecification of goals is a risk we don’t talk enough about, it is the entire framing for how much return you might need and evaluation of various paths to reach that goal. “Taking a risk on the unknown for its own sake is a bad risk strategy.”


My lay advice: Know your goals, mitigate unwanted risk, prepare and position the best you can for when the unknown or unexpected occurs, because life is uncertain, but remember without risk there is no return.


“If we fail to anticipate the unforeseen or expect the unexpected in a universe of infinite possibilities, we may find ourselves at the mercy of anyone or anything that cannot be programmed, categorized, or easily referenced.”

  • Agent Fox Mulder, The X-Files


Tuesday, August 18, 2026

Edward Quince’s Wisdom Bites: Are You Intelligent? The Summary

Let’s close the book on our multi-part exploration of Jason Zweig's brilliant commentary on Benjamin Graham's The Intelligent Investor.

We live in an era of 0DTE options, meme coins, and breathless AI hype. Modern "finfluencers" and cheerleaders scream that "this time is different" and that old rules should be thrown out like scrap paper. But as we’ve tilled the pages of Graham's work, we find that while the characters on the screen change, the beating human heart remains exactly the same. Greed, fear, and the desperate search for a "sure thing" are undefeated. Here is our final map of the territory—the distilled essence of what it truly means to be an intelligent investor.


1. The Great Divide: Investing vs. Speculating

Most market participants are not investors; they are speculators who refuse to admit they are gambling. Graham’s definition is a strict recipe: an investment operation is one which, upon thorough analysis, promises safety of principal and an adequate return. Operations not meeting these requirements are speculative.

Speculation becomes mortally dangerous the moment you begin to take it seriously. If you must speculate, put strict limits on the wager and keep it completely separate from your core portfolio. Yet, the modern "financial video game" is designed to exploit our biological instincts, using addictive app designs and social media hype to turn steady ownership into a casino. The speculative public is incorrigible; in financial terms, it cannot count beyond three. It will buy anything, at any price, if there seems to be some "action" in progress, whether it is a JPEG of a monkey or a viral coin.


2. Mr. Market and the Illusion of Control

To navigate this madness, you must understand the Parable of Mr. Market—a manic-depressive gentleman who shows up on your doorstep daily offering to buy your stocks or sell you his at absurd prices. The classic mistake is answering the door just because he knocks. A long-term investor shouldn't care about market prices; Mr. Market is there to serve you, not to guide you. You do not have to trade with him just because he constantly begs you to.

Instead of anticipating the market—which is the hallmark of speculation—focus on what you can actually control:

  • Your transaction and brokerage costs
  • Your ownership costs (expense ratios)
  • Your expectations for future returns
  • Your risk, through asset allocation
  • Your tax bill, by avoiding rapid churning

Studies show that portfolio policy and asset allocation can be responsible for up to 90% of the volatility experienced and returns earned. Security selection is completely downstream from this asset allocation decision. The hardest work in investing is doing absolutely nothing, but we suffer from an action bias. When volatility spikes, remember Blaise Pascal's advice: all of human unhappiness comes from one simple thing: not knowing how to remain at rest in a room alone.


3. The Math and the Myth of Security Analysis

When you do venture into selecting individual securities, stop looking for overly complex models. Warren Buffett simplified all security analysis down to Aesop's fable of "a bird in the hand is worth two in the bush". To value any asset, you must answer three questions:

  1. How many birds are in the bush?
  2. When will they come out?
  3. What is the risk-free rate?

Ultimately, the absolute most that owners of a business can get out of it in the end is what that business earns over time. But Wall Street loves to build "booby traps" in financial statements. Watch out for "circular financing," where suppliers fund their own buyers to recycle cash flows and fabricate growth. You must do the hard work of digging into the footnotes to understand what a company capitalizes. Finally, adopt the U.S. Air Force rule: "check six". Thinking you are safe is very dangerous; somewhere, there is always a weakness you have to find.


4. The Ultimate Shield: Margin of Safety

In the final chapter, Graham distills the secret of sound investment into three words: "MARGIN OF SAFETY". The margin of safety is, in essence, rendering unnecessary an accurate estimate of the future. If the margin is large, you do not need to predict the future to be protected against the vicissitudes of time.

The primary enemy of the margin of safety is leverage. Levered portfolios face a downside risk to which there is no corresponding upside: the risk of ruin. To survive, you must get through the low points, and the more leverage you carry, the less likely you are to do so. Never forget the six-foot-tall person who drowned crossing the stream that was five feet deep on average. Average conditions don't kill you; the extreme low points do.

Apply this margin of safety to your own mind. Cultivate the intellectual humility to ask: Do I know what I think I know? How do I know what I think I know? What evidence is there that I might be wrong?. Successful professionals succeed because they are disciplined and consistent, refusing to change their approach when it is unfashionable, and paying very little attention to what the market is doing.

As Graham famously concluded: to achieve satisfactory investment results is easier than most people realize; to achieve superior results is harder than it looks.


Thursday, November 27, 2025

Edward Quince's Wisdom Bites: The Thanksgiving Series - Why You Must Pay for a Margin of Safety

Happy Thanksgiving!  

If the future is unknowable—and it is—then what is an investor to do?

Predict harder?
Model with more decimals?
Channel your inner clairvoyant?

No.
You buy a Margin of Safety.
You pay the price of uncertainty upfront, not at the crash site.

Ben Graham’s enduring genius is simple:
Margin of Safety exists to make precise forecasting unnecessary.
It is humility converted into portfolio construction.

Because the greatest danger in markets is not ignorance.
It’s the things we’re certain about that are dead wrong.

Mark Twain captured it beautifully:
“It’s what you know for sure that just ain’t so.”

Margin of Safety also means keeping flexibility—liquidity you didn’t deploy, leverage you didn’t take, options you preserved for when (not if) reality surprises you.

Financial Takeaway:
Survival requires humility.
Protection > Prediction.

Margin of Safety is not a constraint; it is the admission price for staying in the game long enough for your ideas to matter.


Friday, January 2, 2026

Edward Quince's Wisdom Bites: The Great Divide


Welcome back to the digital saloon. With the approval of spot Bitcoin ETFs, predicition markets, and the steady financialization of nearly everything that moves, the line between investing and gambling has blurred faster than a mirage in the desert. This feels like a good moment to return to first principles—specifically, the oldest and most misunderstood divide in finance: investing versus speculating.

These words are often used interchangeably, but they describe fundamentally different activities—different mindsets, different risk profiles, and ultimately, different outcomes.

Two Religions, Not Two Strategies

Robert Hagstrom once put it succinctly at a CFA Institute forum:

An investor thinks first about the asset and second about the price. A speculator thinks first about the price and only later—if at all—about the asset.

Benjamin Graham gave us the canonical definition that still hasn’t been improved upon:

“An investment operation is one which, upon thorough analysis, promises safety of principal and an adequate return. Operations not meeting these requirements are speculative.”

Notice what Graham didn’t say. He didn’t say speculation is immoral. He didn’t say it should be illegal. He said it is different—and dangerous when mistaken for something else.

Speculation is not defined by volatility or novelty. It is defined by dependence on future buyers rather than present value.

The Greater Fool Problem

If you are buying something because you believe someone else will pay more for it tomorrow, you are speculating. Full stop.

This is the “Greater Fool Theory,” and it works—until it doesn’t. As long as a larger fool arrives on schedule, prices rise and confidence grows. But when the chain breaks, value evaporates because it was never anchored to anything real in the first place.

Investing, by contrast, does not require applause. It requires cash flows, balance sheets, and a price that allows for error. It assumes you might be wrong about growth, margins, or timing—and builds in protection accordingly.

Speculation assumes you will be right and on time.

The Margin of Safety Is the Entire Point

The defining feature of investing is not return; it is survivability.

A Margin of Safety allows you to endure disappointment, volatility, and human error. Speculation offers no such buffer. When sentiment turns, there is nothing underneath to stop the fall.

This is why speculative assets tend to require constant narrative reinforcement. They need a hype cycle, a community, a steady stream of validation. If your portfolio collapses without a continuous inflow of belief, you don’t own assets—you own expectations.

And expectations are notoriously fragile.

Modern Markets Make This Harder

One reason this distinction feels blurry today is that modern markets actively encourage speculation. Financial products are packaged, marketed, and distributed in ways that reward turnover, excitement, and narrative simplicity.

This doesn’t make speculation evil—but it does make self-awareness essential. Problems arise when people believe they are investing while behaving like speculators, or worse, when they lever speculative positions under the illusion of safety.

Both activities exist. Both attract capital. Only one is built to survive disappointment.

The Lesson

Be honest about what you are doing.

If you are underwriting cash flows, assessing downside risk, and buying with room for error, you are investing—even if prices fluctuate.

If you are relying on price momentum, social consensus, or future enthusiasm to justify today’s valuation, you are speculating—even if the asset feels “inevitable.”

Both paths can lose money. Only one offers a Margin of Safety.

If your portfolio requires a hype-man to maintain its value, you are not investing—you are holding a hot potato and hoping the music doesn’t stop on your turn.

XTOD

“The world is full of foolish gamblers, and they will not do as well as the patient investor.” — Charlie Munger

Tuesday, November 4, 2025

Edward Quince's Wisdom Bites: The Marks Series - The Futility of Macro Forecasting and the Value of "I Don't Know"

Edward Quince (EQ): Howard, one of the prevailing themes on this blog is the inherent uncertainty in financial markets, often summarized by the difficult answer, "I don't know". You've written extensively about the value—or lack thereof—in forecasting the future. Why is macro forecasting an area you advise investors to largely ignore?

Howard Marks (HM): Macro predictions are unlikely to give you an edge. There are two main problems. First, we don’t know what’s going to happen. The world is too complex, too erratic, and too full of surprises to make spot forecasts of anything of significance. Second, even if a forecast turns out to be correct, we don't know how the markets will react to what actually does happen. Forecasting is uncertain, so it's safer not to try to time markets based on predictions.

EQ: You mention that in efficient markets, correct forecasts are potentially very profitable, but also hard to make consistently. Is the consensus view of economists any better?

HM: The consensus view is usually an extrapolation of the current condition and is already embedded in the price of an asset. Most forecasts tend to cluster around historic norms and call for only small changes, underestimating the potential for radical change. If you are merely forecasting the most likely outcome, you are highly unlikely to hang your spreadsheet on predicting a discontinuity. Furthermore, most forecasters have average ability, and we rarely see their track records.

EQ: You advocate for the "I don't know" school of investing. What does this intellectual humility require of an investor in terms of action?

HM: The "I don't know" investor must face up to the uncertainty that surrounds the macro future. Instead of trying to divine the next economic move, we should devote ourselves to specialized research in market niches that others find uninteresting or overly complicated. We will continue to try to "know the knowable". This means focusing on micro factors relating to companies, assets, and securities where it is possible to obtain a knowledge advantage through the expenditure of time and effort. By concentrating on avoiding pitfalls and investing based on in-depth analysis, conservatively estimated tangible values, and modest purchase prices, we can proceed without relying on macro-forecasts.

EQ: So, the valuable forecasts are those that call for radical change, but those are rarely right. In lieu of perfect foresight, how do we protect ourselves?

HM: We must acknowledge the limits of our knowledge. This humility should drive us to employ the Margin of Safety. The margin of safety is, in essence, rendering unnecessary an accurate forecast of the future.

The Edward Quince Takeaway

Embrace intellectual humility: recognize that "Nobody knows" the macro future, and those who claim certainty should be met with skepticism. Focus your efforts on knowing the knowable—deep, bottom-up research in niche areas where superior insight is achievable—and rely on a robust Margin of Safety rather than unreliable predictions.


Wednesday, December 13, 2023

FOMC Recap: Performance Review Edition

  • As expected the FOMC remained on hold for the third straight meeting, leaving the Fed Funds Target range at 5.25% to 5.50% with no changes to QT or other policies.
  • The language in the FOMC Statement was less firm on the possibility of additional rate hikes.
  • The Dots showed the Fed forecasting a 50bp lower 2023 Core PCE rate relative to estimates from September, as well as a 50bp reduction, from 5.1% to 4.6%, in the Median 2024 Fed Funds dot relative to September.
  • Powell indicated the Fed remains fully committed to returning inflation to 2% goal, characterizing the current stance of policy as restrictive and cited the long and variable lags associated with monetary policy.
  • Powell indicated that FOMC participants believe we are at the peak of interest rates.
  • "Normalization Cuts" were discussed in the press conference, albeit poorly, but Powell acknowledged there was discussion as to when to start cutting rates as inflation cools.
  • 2Y yields were down 20bps following the FOMC Statement and fell a further 10bps as Powell spoke, breaching 4.45%.
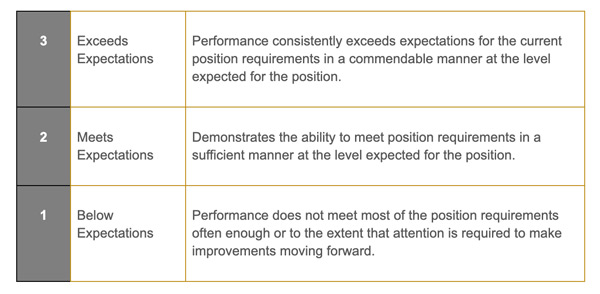
Every year most of us are forced to write down our professional goals, usually cascading down from company and team goals to you as the individual.  Now is that time of year where many organizations are conducting their performance reviews.  With that in mind, there is no better time than now to review the FOMC's performance for this year.

As is the case with any good performance appraisal, you should start with some objective criteria against which you are measuring performance.  In the case of the FOMC, Congress specified the goals of the Fed as: (1) maximum employment, (2) stable prices, the so called "dual mandate", but there is an often forgotten third mandate in the amended Federal Reserve Act of 1977 and that is (3) moderate long-term interest rates.

Now for the appraisal:
On Maximum Employment - Exceeds Expectations:  we came into 2023 with forecast for recessions which would have included job losses.  The unemployment rate remains below 4% and though there may be some signs of labor market weakness, it's hard to say that the jobs picture isn't more robust than what most expected at the start of the year.

On Inflation - Needs Improvement/Below Expectations - you can argue with me until you are blue in the face that the Fed deserves a better grade here given the rapid disinflation seen in PCE and CPI data, but perhaps an example will sway you.  Assume that you, as an employee, start the year with your boss telling you that the number of errors (maybe it's trading errors, maybe it's quality defects) you made was way to high last year and that the number of errors to be tolerated was 2.  Your boss gave you a second chance last year because they knew there were some extenuating circumstances and you hadn't made too many of these types of errors recently, so your boss let you overshoot the error quota for a while (your boss even allowed you to change your the policy goal to "FAIT"), but said they weren't going to tolerate errors above 2 forever.  You go into 2023 knowing you have to bring the level of errors back to 2, so you continue to be aggressive with your policies, they seem to be working, but your errors are still double what you were told you needed to achieve.  Well, that's the Fed, they have that 2% inflation goal, but we're sitting here today a year later and we're still nearly double that rate.  You wouldn't get away with that in your performance review, would you?  You can tell your boss that everyone thinks your error rate will come down in the future, expectations are that they will, but would your boss keep giving you a pass?

On Moderate Long-Term Interest Rates - Meets Expectations - in the Federal Reserve's publication, "The Fed Explained: What the Central Bank Does" it states: ".. long-term interest rates remain moderate in a stable economy with low expected inflation...".  This third mandate is never really mentioned because it seems to be dependent upon the first two topics.  Certainly yields are higher than some people expected as the start of the year and they seem more moderate than they were when most of the curve was very low across the curve in the 2010's. But with so much uncertainty around things like R* and U* it's hard to do better than "meets" here.  I think the Fed did a better job on meeting or exceeding "volatile" long-term interest rates this year than they did on meeting the definition of "moderate". Arguably the rating could be worse as the Fed seemed to be relying upon tightening of financial conditions to do some work for them, with that tightening coming from higher long-term rates, and that seems to be going the wrong way as financial conditions have eased into year end.

Most reviews also include a section where the manager provides some narrative assessment of how things are going for the employee being reviewed.  Here's mine for the Fed:
While progress has been made towards your goals, it's unclear how much of the success is attributable to your performance. You haven't done a great job of explaining your reaction function and often the market discounts what you are saying and believes you'll abandon your goals early if they complain loud enough.  What is your reaction function? Are there rules you look at and follow to help you achieve your goals? 

Your colleagues noted you did a lot of talking and many times that talking was distracting. We value a high "sit-next-to" factor here and it seems you can cause a lot of people anxiety. It seems like you spend most of your day just talking, when do you get work done? Oh, I see you think your job is mostly talking, propaganda, and suasion. We'll take this under consideration in 2024 goal setting.

Your track record of forecasting is not good. In 2024 maybe you should focus on the concept of "Margin Of Safety".  In the words of Benjamin Graham in his classic book "The Intelligent Investor", Margin Of Safety is "in essence, that of rendering unnecessary an accurate forecast of the future".  I know you're trying to balance both risk to unemployment and inflation, but look at where you need improvement, perhaps you might need to apply the Margin Of Safety concept to your inflation mandate.

Lastly, your performance was mixed on supervising your direct reports. Remember how several banks failed?  You did a nice job of limiting the impact, but some find it troubling how this happened in the first place and how you seemed to miss the build up of economic and financial risk in years prior as well. 

As we head into 2024, as you stay employed in your job of steering the most important economy in the world, I will remind you of some advice from the late, great Charlie Munger,  "Nobody survives open heart surgery better than the guy who didn't need the procedure in the first place."  You say you'd rather be Volcker than Burns, your goal for 2024 is to get inflation back to 2%.  Let's try to get there without breaking something that will require open heart surgery.


Wednesday, November 5, 2025

Edward Quince's Wisdom Bites: The Marks Series - Risk Control and the Road to Riches

Edward Quince (EQ): Howard, your emphasis on risk control is a cornerstone of your investment philosophy. We frequently highlight Morgan Housel’s insight that "survival is the only road to riches". How critical is it for investors to prioritize protection over maximizing returns?

Howard Marks (HM): Survival is indeed the only road to riches. You must strive to maximize return only if losses would not threaten your survival. We believe firmly that “if we avoid the losers, the winners will take care of themselves”. We aim for a high batting average, not home runs. Most of the investing careers that produce the best records are notable at least as much for the absence of losses and losing years as they are for spectacular gains.

EQ: That sounds like a defensive approach, focused on avoiding mistakes. How do we define that necessary defense?

HM: Investing defensively requires prioritizing the avoidance of losses. The key concept here is the Margin of Safety. Margin of safety means you shouldn’t pay prices so high that they presuppose things going right. Instead, prices should be so low that you can profit—or at least avoid loss—even if things go wrong. This buffer ensures you survive the low points.

EQ: But when markets are soaring, focusing on risk control can feel like a penalty. Investors worry about "opportunity cost"—missing out on gains.

HM: This is the core tension. We constantly deal with two main risks: the risk of losing money and the risk of missing opportunity. Investors should strive to balance both. However, if you opt for defense, you should get higher lows but also lower highs. We tell people that in good times, it’s good enough to be average, because we set up our portfolios to outperform in bad times. When others are euphoric, that puts us in danger. It is by being willing to cede much of the return distribution lying between “solid” and “maximum” that we prioritize survival. You can completely avoid one risk or the other, or you can compromise, but you can’t eliminate both.

EQ: In short, this philosophy requires tremendous fortitude and a willingness to look "dowdy" during bull markets.

HM: Indeed. You must cultivate humility, acknowledge uncertainty, and make prudent decisions. Investing scared will prevent hubris and increase the chances that your portfolio is prepared for things going wrong. If nothing goes wrong, the winners will take care of themselves. You never want to be caught "swimming without a bathing suit" when the tide goes out.

The Edward Quince Takeaway

Prioritize survival above all else, remembering that the absence of losses contributes more to long-term success than spectacular gains. Build your strategy around a sufficient Margin of Safety—the flexibility, prudence, and liquidity needed to navigate the inevitable low points without risking permanent loss of capital.


Friday, March 27, 2026

Edward Quince’s Wisdom Bites: The Stoicism of Preparation

We spend our days refreshing screens, reading the latest CPI prints, and hanging on every carefully parsed word of the Federal Reserve Chairman. We act as if the economy is a machine that can be perfectly predicted if we just look at the data long enough.


But the future is inherently uncertain. "Black swans," financial crises, and exogenous shocks arrive without warning. Today’s wisdom is about recognizing what you can control, and ignoring what you cannot.


The Wisdom Bite:

“If you are confident you have done everything possible to prepare yourself, then there is nothing to fear. There’s no stress in losing under those circumstances. It just wasn’t meant to be.” – Michael Jordan


In investing, preparation is the exact equivalent of Benjamin Graham’s ultimate rule: the Margin of Safety. The core tenet of the Margin of Safety is rendering an accurate forecast of the future completely unnecessary.


You prepare by refusing to overpay for assets, no matter how rosy the current economic consensus appears. You prepare by maintaining liquidity, acknowledging that cash is a call option on every asset class without an expiration date. You prepare by rigorously avoiding excessive leverage, ensuring that your portfolio can survive the inevitable market panics without being forced to liquidate at the exact wrong time.


If you have built this defensive architecture into your financial life, a market drawdown is no longer a source of terror. It is simply a temporary mark-to-market event. You have done everything possible to prepare yourself; the rest is out of your hands.


The Wisdom Bite:

"Life moves pretty fast. If you don't stop and look around once in a while, you could miss it." – Ferris Bueller


Once you have prepared your portfolio for survival, the most crucial next step is to walk away from it.


The financial industry is engineered to trigger your anxiety, pumping out 17 hours of live television a day to convince you that you need to trade. But reacting to this constant "hubbub" guarantees poor performance. The true objective of wealth accumulation is not to chain yourself to a glowing monitor tracking decimal points; it is to maximize your independence and autonomy. If you cannot enjoy your weekends—or your weekdays—without checking stock prices, your portfolio owns you, not the other way around.


The Financial Takeaway:

You cannot control the macro-economy, and you cannot predict the next crisis. Build your portfolio with extreme prudence, demand a wide margin of safety, and eliminate leverage. Once you have prepared your financial fortress to withstand the storm, close the terminal. Go outside. The greatest dividend money pays is the freedom to focus your time on the people and pursuits that actually matter.


Monday, July 28, 2025

Edward Quince's Wisdom Bites: The Hard Truth of Fiscal Discipline – Or, Why We Keep Kicking the Can

Welcome back to Edward Quince's Wisdom Bites, your daily reminder to cut through the noise and focus on what truly matters. Today, we're diving into a topic that feels perennially relevant, yet consistently misunderstood: fiscal discipline. While the market gyrates and pundits clamor, the wisdom of the past, and a dash of intellectual humility, might just offer the clearest path forward.

The Elephant in the Room: Mounting Debt and Deficits

It seems that every day brings fresh warnings about the U.S. fiscal situation. From Moody's putting U.S. sovereign debt on negative watch to calls about a "Minsky moment" from a fiscal situation deemed "impossible," the chatter is omnipresent. There's a persistent concern among investors about rising U.S. debt levels. Even Fed Chair Powell has acknowledged the national debt as unsustainable. We're talking trillions added to the debt, often with hundreds of billions more if expiring provisions are extended. It appears that policymakers sometimes act as if the answer to all problems is simply more government spending, as if there's no such thing as an uncovered deficit.

Historically, Alexander Hamilton warned Congress in 1790 that "the creation of public debt should always be accompanied with the means of extinguishment" as "the true secret for rendering public credit immortal". For the first 175 years of the nation, the U.S. largely adhered to this "Hamilton Norm," issuing large quantities of public debt only during emergencies. One can certainly wonder if we've violated that norm, and if it matters.


The Fiscal Theory of the Price Level (and Why it Matters)

While Modern Monetary Theory (MMT) might "diss" the idea of bond vigilantes and suggest governments can finance all spending without borrowing or taxes, other compelling theories offer a starkly different view. John Cochrane, a leading proponent of the Fiscal Theory of the Price Level (FTPL), suggests that if fiscal policy is undisciplined, the Fed's actions alone may not lower inflation. In fact, if the Fed raises interest rates, it raises interest costs on the debt, and if taxes don't rise or spending doesn't fall to pay those costs, there's "no reduction in inflation". He calls this "unpleasant interest rate arithmetic".

The FTPL posits that inflation occurs if debt exceeds faith in a country's long-run ability and will to repay it. This theory suggests that the Central Bank can only "move inflation around over time," and ultimately doesn't have full control if fiscal policy isn't consistent with price stability. It highlights the "real danger" that comes from "encouraging or inadvertently tolerating rising inflation and its close cousin of extreme speculation and risk taking".

The Fed's Dilemma: Independence vs. Politics

The Fed may believe a certain policy is correct but worry it will appear politically motivated. Peter Stella's definition of central bank independence is "the ability to raise interest rates when the Treasury doesn't want you to," which is almost always the case due to the cost of debt. Powell has stated the Fed "do not consider politics in our decisions. We never do. And we never will". However, the macroeconomic models themselves implicitly include some budget constraints and fiscal-monetary coordination. If fiscal policy is the major driver of inflation, how is the Fed supposed to fulfill its price stability mandate?

What's the Wise Play? Beyond the Headlines.

In a world loud with information, where everyone has a "take," the key is often to mute the unnecessary and discern what truly matters. As the wisdom from the blog frequently emphasizes, "Clarity comes from subtraction, not addition. Remove the noise, the distractions, and the unnecessary. What truly matters will emerge".

Here's some wisdom to help you navigate the fiscal noise:

• Embrace Intellectual Humility: Recognize that forecasting the future is a "fool's errand," and even "experts" are often wrong. As Morgan Housel wisely noted, "Real optimists don't believe that everything will be great...Optimism is a belief that the odds of a good outcome are in your favor over time, even when there will be setbacks along the way".

• Focus on What You Can Control: Your behavior matters more than any forecast. Instead of reacting to every headline, cultivate discipline and a robust process. As Charlie Munger advised, "It's waiting that helps you as an investor, and a lot of people just can't stand to wait".

• Prioritize a Margin of Safety: Benjamin Graham's concept of a "margin of safety" is about "rendering unnecessary an accurate forecast of the future". This means building flexibility, avoiding excessive leverage, and having a buffer to withstand unexpected events. "Know your goals, mitigate unwanted risk, prepare and position the best you can for when the unknown or unexpected occurs, because life is uncertain, but remember without risk there is no return".

• Learn from History, But Don't Over-predict: "History doesn't repeat, but human nature does". Studying past financial disasters can impart "invaluable lessons on what to do and what not to do at far lower cost than making the mistakes oneself". However, be wary of thinking "this time is different".

• Question the "Why": Understand the motivations and incentives of those providing information. As Charlie Munger said, "I never allow myself to have an opinion on anything that I don't know the other side's argument better than they do".


Ultimately, fiscal discipline—or the lack thereof—has profound consequences. While you can't control government policy, you can control your own approach to navigating an uncertain world. Remember, "The greatest shortcoming of the human race is our inability to understand the exponential function". This applies not just to compounding wealth, but also to compounding problems.


Edward Quince’s Wisdom Bites: OPV Page 419

  “The best business is where no one else competes, where you buy for one cent and sell for a dollar and it's habit-forming and no one e...